
A large depreciation deduction can look like an easy win until you discover that you cannot use the loss. Before buying a study, ask what is cost segregation in real estate, how much of the deduction you can actually claim, and what happens when you sell. Those three questions separate useful tax planning from an expensive report.
For California rental owners, the analysis also needs two sets of numbers: federal and state. This guide answers the questions investors should resolve before authorizing a study, using transparent examples rather than guaranteed savings.
This information is current as of November 7, 2026. Tax laws change frequently. Verify current IRS and California Franchise Tax Board guidance before implementing a transaction. Examples are hypothetical and are not individualized tax advice.
What Is Cost Segregation in Real Estate, in Plain English?
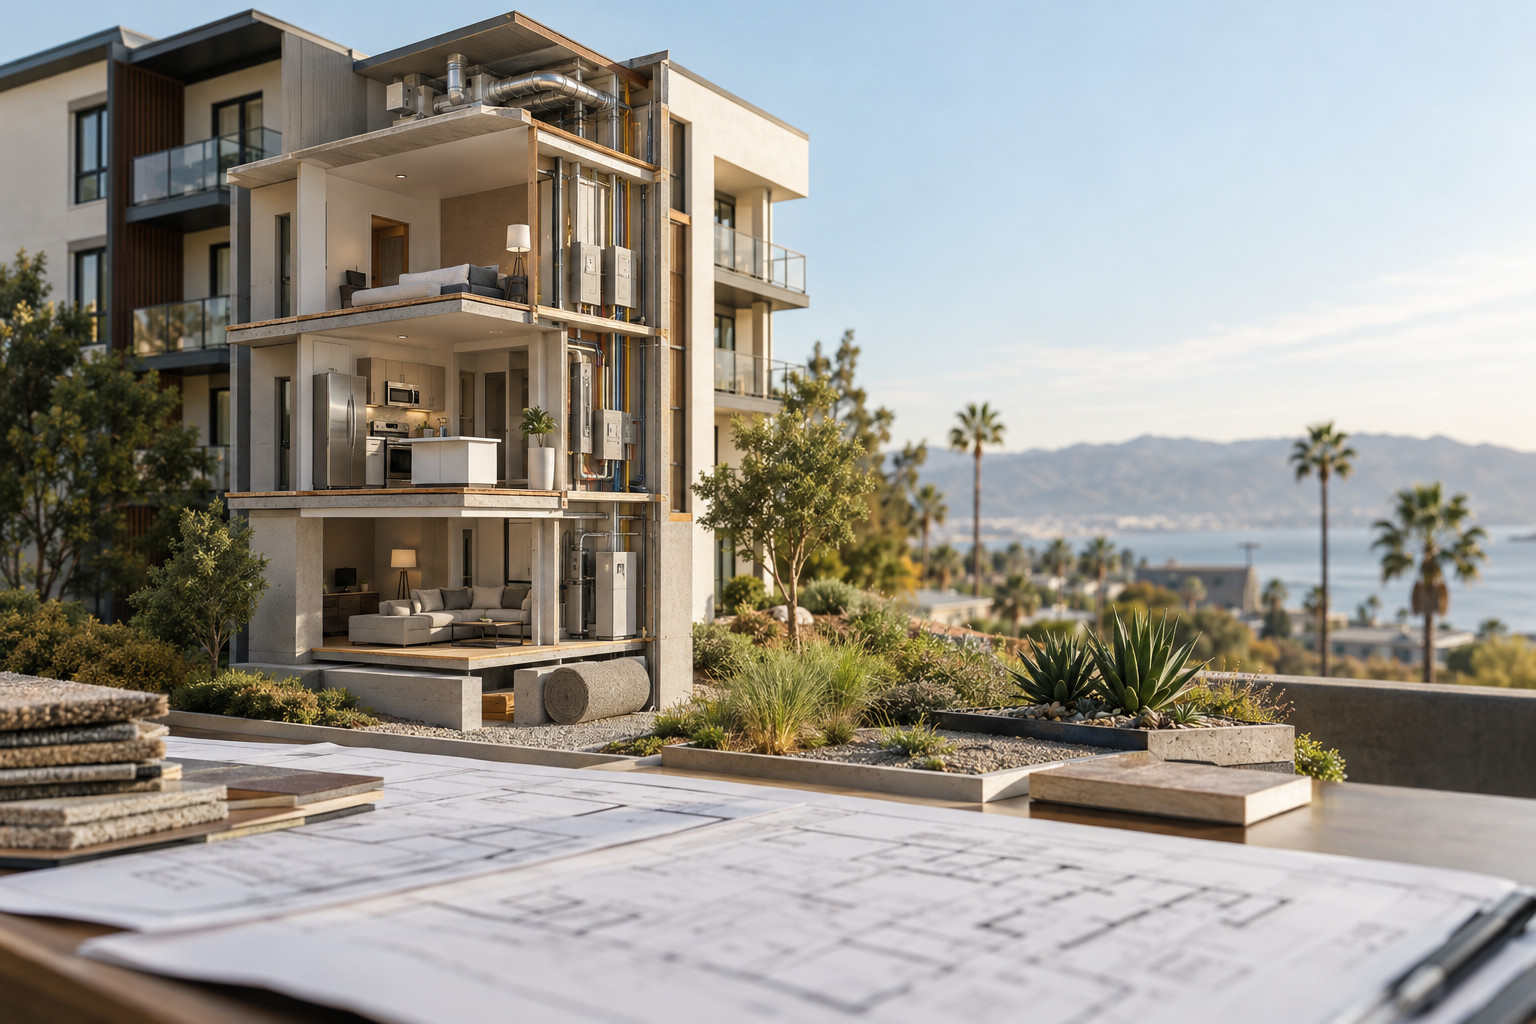
Cost segregation is an analysis that separates a property’s depreciable cost into components with different tax recovery periods. Instead of depreciating every eligible dollar as part of a long-lived building, an owner identifies qualifying assets that can be deducted sooner. Land remains nondepreciable.
Quick answer: A study can accelerate deductions for qualifying personal property and land improvements, but it does not create additional purchase price or guarantee usable tax savings. Eligibility, timing, loss limitations, California adjustments, and eventual sale treatment determine the actual benefit.
What gets separated?
Residential rental buildings generally use a 27.5-year federal recovery period, while nonresidential buildings generally use 39 years under the general depreciation system. Certain assets may qualify for shorter periods, commonly five, seven, or fifteen years. Alternative depreciation system requirements can change that treatment.
| Property component | Typical federal treatment | Important limitation |
|---|---|---|
| Land | Not depreciable | Allocate separately |
| Residential rental structure | Generally 27.5 years | Classification matters |
| Commercial structure | Generally 39 years | Exceptions may apply |
| Qualifying appliances or carpeting | Often five years | Facts control classification |
| Qualifying exterior improvements | Often fifteen years | Separate land from improvements |
A building’s general electrical system does not become five-year property just because electricity serves an appliance. Classification depends on function, installation, applicable authority, and supporting facts. The IRS Publication 946 depreciation rules explain recovery periods, conventions, and depreciation methods.
The useful answer to what is cost segregation in real estate is therefore not “a bigger write-off.” It is a defensible allocation that changes when eligible costs are recovered.
How Much Can an Investor Actually Save?
Start with incremental deductions, not the study’s headline depreciation total. If you would already receive $30,000 of regular depreciation, a proposed $150,000 total deduction represents a $120,000 acceleration before other adjustments. Calling the entire $150,000 an additional benefit overstates the comparison.
A simple federal calculation
Suppose an investor buys a rental for $1,200,000 and reasonably allocates $240,000 to land. The remaining $960,000 is depreciable basis before other capitalized adjustments. Assume a qualified analysis identifies $192,000 of eligible shorter-lived assets.
For illustration, assume the completed federal calculation produces $180,000 more first-year depreciation than the no-study calculation. At an assumed 32% marginal federal rate, that acceleration could reduce current federal tax by $57,600 if every incremental dollar is currently deductible. This is timing-related tax reduction, not a promise of permanent savings.
Three owners, three different outcomes
- W-2 household: An engineer earning $260,000 receives an additional $60,000 passive rental loss. Without passive income or another applicable exception, the current wage-offset benefit may be $0. The loss generally carries forward.
- 1099 professional: A consultant earns $180,000 from work and $40,000 of net passive rental income before the extra deduction. A $60,000 additional rental deduction might offset the $40,000, while the remaining $20,000 is suspended, subject to the full limitation analysis.
- High-net-worth investor: An owner with $100,000 of otherwise taxable passive income and a usable $70,000 incremental deduction could see $24,500 of federal income tax reduction at an assumed 35% rate, before other interactions.
These examples explain why what is cost segregation in real estate must be answered at the taxpayer level. Two people can own identical buildings and receive very different current benefits.
KDA’s cost segregation advisory services can help connect a property’s asset analysis with the owner’s broader tax position. A useful proposal should compare current deductions, suspended losses, study fees, and expected holding period.
KDA Case Study: Rental Investor Evaluates a Study Before Buying It
Illustrative planning scenario, not a verified client result: Consider a California investor with $300,000 of W-2 household income and $90,000 of net taxable passive income from existing rentals. The investor acquires another rental and receives a proposal emphasizing a large accelerated depreciation deduction.
The problem is not whether a report can identify shorter-lived assets. It is whether the resulting loss can produce enough current value to justify the fees and future reporting burden. In a KDA-style advisory engagement, the first step would be to reconcile purchase basis, review passive income sources, check prior depreciation, and model federal and California results separately.
Assume that review supports $80,000 of incremental depreciation, fully usable against qualifying passive income. At an assumed 32% marginal federal rate, the modeled first-year federal tax reduction is $25,600. Assume the investor pays $6,000 for the combined study and advisory work; that fee is hypothetical, not a KDA quote.
The modeled gross tax-benefit-to-fee ratio is approximately 4.27 times. Subtracting the fee leaves $19,600 of first-year cash benefit, or approximately 3.27 times the fee, before fee-related tax effects, state adjustments, financing costs, and future recapture. The decision would still require reviewing the intended sale date and documentation quality.
Ready to see how we can help you? Explore more success stories on our case studies page to discover proven strategies that have saved our clients thousands in taxes.
Which Rules Can Block the Deduction?
Does owning an LLC make rental losses deductible against wages?
No. An LLC is a legal entity, not an automatic override of federal loss limitations. A single-member LLC may be disregarded for federal income tax purposes, while a multi-member LLC commonly files as a partnership unless a different classification applies.
The owner still needs to examine basis, at-risk limits, passive activity rules, and any applicable excess business loss limitation. Partnership allocations and partner-level basis can make entity-owned property especially sensitive. Review the IRS Publication 925 passive activity and at-risk rules before assuming that a depreciation loss offsets salary.
Does real estate professional status solve everything?
No. Federal real estate professional status generally requires more than 750 hours in qualifying real property trades or businesses and more than half of the individual’s personal service time in those activities. Material participation in the relevant rental activity is a separate requirement.
A full-time W-2 employee cannot simply buy property and elect to ignore those tests. Spousal participation, grouping elections, and contemporaneous records require careful review. The special allowance for certain actively participating rental owners also has income-related limits; it is not a universal wage-offset rule.
What about short-term rentals?
Some short-stay arrangements fall outside the passive rules’ rental-activity definition. That does not automatically make their losses nonpassive. Average customer use, services provided, personal use, and material participation all matter.
If you are asking what is cost segregation in real estate because someone promised a short-term rental would erase your paycheck taxes, request the participation analysis in writing before relying on the projection.
How Do Federal Bonus Depreciation and California Rules Differ in 2026?
Cost segregation identifies asset categories. Bonus depreciation is a separate federal rule that may accelerate qualifying asset deductions further. The two concepts work together, but they are not interchangeable.
Is the entire building eligible for bonus depreciation?
No. The ordinary residential or commercial building itself generally is not eligible. Qualifying shorter-lived components may be. Federal law restored 100% bonus depreciation for eligible property acquired and placed in service after January 19, 2025, subject to qualification requirements and transition rules.
Do not determine eligibility from a closing date alone. Binding contracts, acquisition rules, related-party restrictions, prior use, placed-in-service timing, and elections can affect treatment. Use the IRS guidance on current federal tax law provisions and the applicable return instructions rather than an outdated phase-down chart.
Does California give the same deduction?
California generally does not conform to federal bonus depreciation. That means an accelerated federal result can require state depreciation adjustments and separate basis tracking. Do not multiply a federal deduction by a combined federal-and-California rate and call the answer savings.
Review the FTB instructions for individual depreciation adjustments for the adjustment framework, and use the applicable 2026 form and entity instructions when available. An individual return, partnership, and corporation may require different schedules.
This federal-state split is a central part of what is cost segregation in real estate for California investors. The study must support a federal classification analysis without obscuring the separate state computation.
How Do You Implement a Defensible Study?
Begin with a feasibility review before commissioning a full report. No universal purchase-price threshold makes a study worthwhile. The available deduction, current ability to use it, scope of the property, fee, and sale horizon matter more than a marketing cutoff.
- Confirm ownership and basis. Gather the closing statement, purchase agreement, land allocation support, and capitalized acquisition costs.
- Establish placed-in-service dates. Document when the property and later improvements were ready and available for their intended income-producing use.
- Collect physical records. Supply plans, photographs, renovation invoices, contractor detail, and any prior asset schedules.
- Model deduction usability. Review passive income, participation, entity allocations, basis, and at-risk exposure before accepting a projected benefit.
- Review the report’s methodology. Require asset descriptions, allocation support, recovery periods, and reconciliation to the property’s total depreciable basis.
- Implement both tax schedules. Update federal and California depreciation records, required elections, and any accounting-method filings.
What should the report explain?
A credible report should explain why an asset belongs in a particular class, not merely assign a percentage to “personal property.” It should reconcile to the books and distinguish qualifying components from structural systems.
The IRS Cost Segregation Audit Technique Guide describes examination considerations and study-quality issues. It is an examination resource, not IRS approval of a provider or a guarantee that a proposed allocation will survive review.
Can you study a property purchased years ago?
Often, yes. A change from an impermissible depreciation method may involve Form 3115 and a Section 481(a) adjustment, which reconciles prior depreciation treatment. Other circumstances may require a different correction procedure.
Do not assume every catch-up deduction belongs on an amended return. The IRS instructions for Form 3115 describe accounting-method procedures. Filing timing, eligibility, and the appropriate change number need professional review.
When evaluating what is cost segregation in real estate for an older holding, include implementation costs and missing-record risk in the decision. A cheap report can become expensive if the return work is excluded.
What Happens When You Sell, and When Should You Wait?
Will accelerated depreciation increase tax on a sale?
It can. Depreciation reduces adjusted basis, which can increase taxable gain. Gain attributable to certain personal-property depreciation can trigger ordinary-income recapture under Section 1245; real-property gain follows different rules, including potential unrecaptured Section 1250 gain treatment.
Review the IRS Publication 544 rules for property dispositions. Sale-price allocation among assets matters. Federal and California adjusted bases may differ, creating another reconciliation rather than one identical gain figure.
Does a 1031 exchange eliminate every consequence?
No. Section 1031 generally applies to qualifying real property, and separately classified personal property requires analysis. Do not assume a planned exchange automatically shelters every component’s gain or eliminates prior depreciation consequences.
What questions should you ask before signing?
- How much additional depreciation is projected compared with doing nothing?
- How much can I use this year, rather than carry forward?
- Are state adjustments and accounting-method filings included in the fee?
- Who supports the classifications if the IRS asks questions?
- What happens under a sale in two, five, or ten years?
Proceed when a supportable classification analysis produces meaningful usable value after fees and holding-period effects. Consider waiting when losses will remain suspended, a near-term sale weakens the timing benefit, records are incomplete, or the provider will not explain its assumptions.
The final answer to what is cost segregation in real estate is a planning decision, not just an engineering report. A strong result connects the building, the taxpayer, the return, and the eventual exit.
Ready to Reduce Your Tax Bill?
KDA Inc. specializes in strategic tax planning for business owners, S Corps, LLCs, and high-net-worth individuals. Book a personalized consultation and walk away with a clear plan.
Find Out Whether Your Property Produces Usable Tax Savings
Before paying for a study, find out whether accelerated depreciation can actually improve your cash position. Bring your closing statement, current depreciation schedule, latest return, and expected holding period. KDA can help evaluate deduction usability, California adjustments, implementation requirements, and exit tradeoffs. Book your property-specific cost segregation consultation and make the decision with a tax model, not a sales estimate.



