
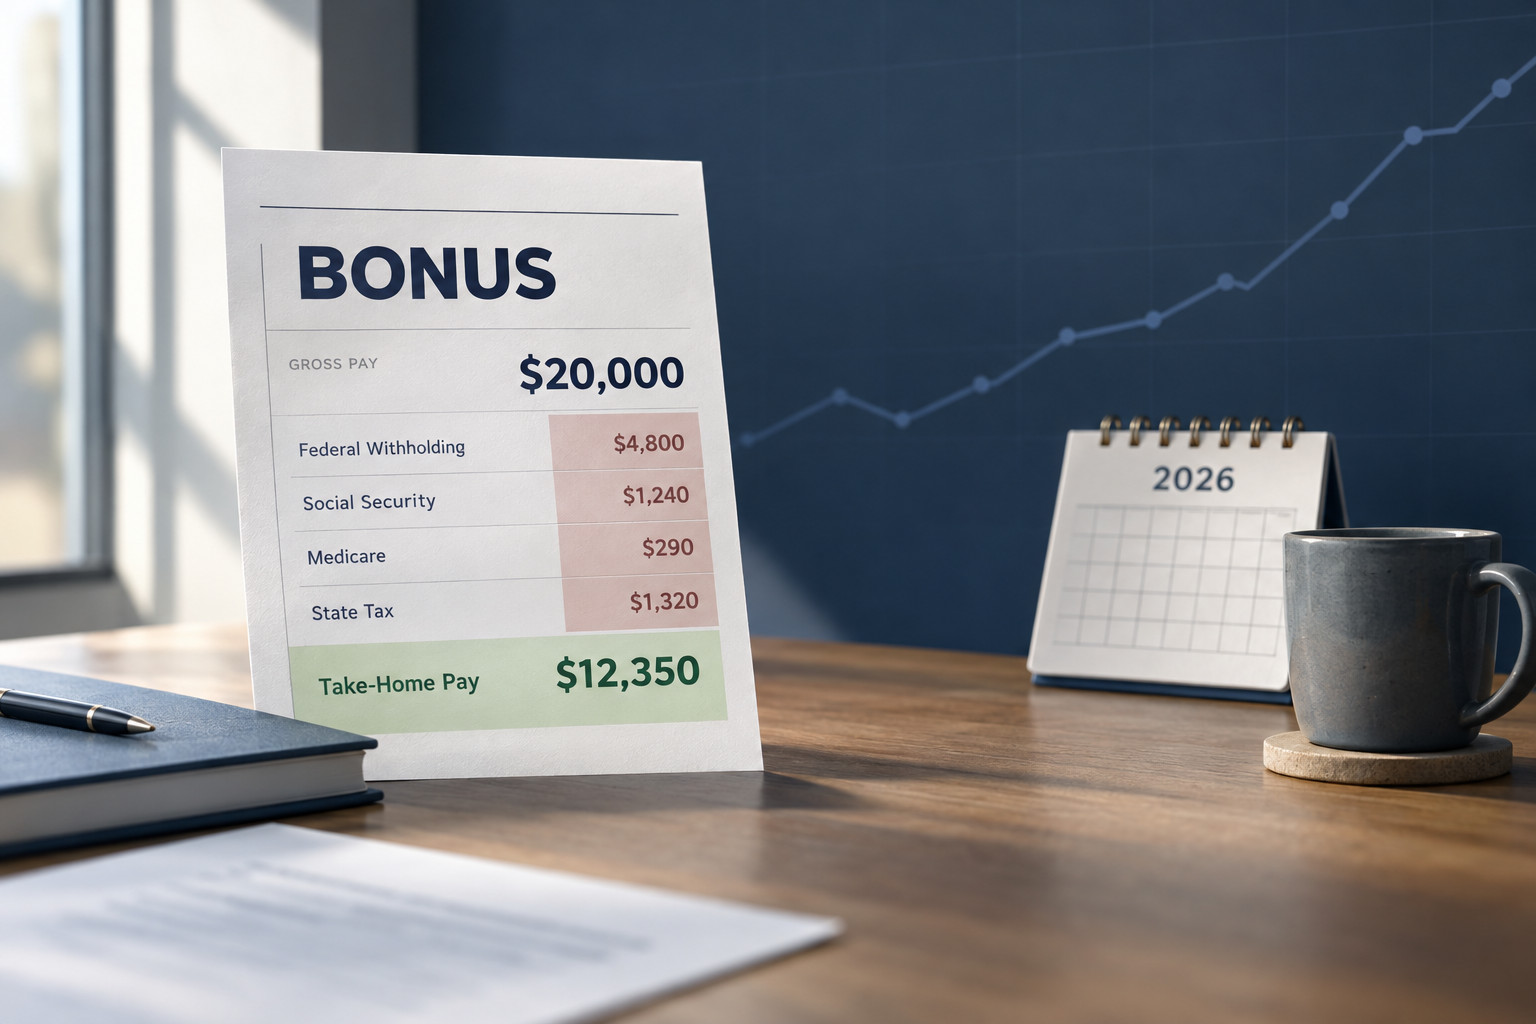
You earned a $20,000 bonus. You did the math in your head, expected roughly $15,000 to hit your account, and then watched $12,800 land instead. Your first reaction was that your employer made a mistake or that bonuses get punished by a special penalty rate. Neither is true. The question of what is bonus tax rate 2026 has a clean answer, and once you understand it, you stop reacting to your pay stub and start planning around it.
Here is the part most people never hear: the amount pulled from your bonus is a withholding estimate, not a tax bill. Withholding is a down payment. Your actual tax is settled on your return in April. That gap between what was withheld and what you actually owe is where real money gets recovered or lost.
Quick Answer: What Is the Bonus Tax Rate in 2026?
There is no separate bonus tax rate. For 2026, employers using the percentage method withhold a flat 22 percent federal income tax on supplemental wages up to $1 million in a calendar year, and a mandatory 37 percent on any supplemental wages above that $1 million threshold. Social Security, Medicare, and state withholding apply on top of that. Your bonus is taxed at your ordinary marginal rate when you file, which may be higher or lower than 22 percent.
Key Takeaway: A 22 percent federal withholding on a bonus does not mean your bonus was taxed at 22 percent. It means 22 percent was prepaid.
What Is a Supplemental Wage, and Why Does It Matter?
Supplemental wages are payments made outside your regular pay cycle. The IRS lists bonuses, commissions, overtime, severance, back pay, accumulated sick leave payouts, awards, prizes, retroactive raises, and taxable fringe benefits in this category. Restricted stock units that vest and get reported on your W-2 are also treated as supplemental wages by most payroll systems.
The reason the label matters is mechanical. Payroll software cannot predict your full-year picture from one irregular payment. If your employer dropped a $20,000 bonus into a normal biweekly run, the system would briefly assume you earn $20,000 every two weeks and withhold as if you were a $520,000-per-year earner. To avoid that distortion, the IRS allows two approved methods for withholding on supplemental wages, described in IRS Publication 15, Circular E, Section 7.
The Percentage Method
Your employer separates the bonus from your regular wages and applies a flat 22 percent federal rate. This is the most common approach because it is simple and defensible. It is also why nearly every bonus stub in America shows the same federal percentage, regardless of whether the recipient earns $70,000 or $400,000.
The Aggregate Method
Your employer combines the bonus with your most recent regular paycheck, calculates withholding on the total using your Form W-4 elections, subtracts what was already withheld on the regular wages, and withholds the difference from the bonus. For a high earner, this often produces withholding above 22 percent. For someone in the 12 percent bracket, it can produce less.
Why Your Bonus Lost More Than 22 Percent
The 22 percent figure only covers federal income tax. Several other line items hit the same dollars. Here is where a $20,000 bonus actually goes for a California W-2 employee who has not yet hit the Social Security wage cap.
| Withholding Item | Rate | On $20,000 |
|---|---|---|
| Federal income tax (supplemental) | 22.0% | $4,400 |
| Social Security | 6.2% | $1,240 |
| Medicare | 1.45% | $290 |
| California supplemental income tax | 10.23% | $2,046 |
| California SDI | 1.2% | $240 |
| Total withheld | 41.08% | $8,216 |
That is the real explanation behind the $12,800 deposit. Nothing was miscalculated. Five separate obligations stacked on one payment. California applies a 10.23 percent supplemental withholding rate specifically to bonuses and stock options, which is higher than the 6.6 percent it applies to other supplemental payments. That single detail surprises more Bay Area and Southern California earners than any other item on this list.
If you want to see exactly how your own number lands before payday, run the figures through this bonus tax calculator and compare the output to your stub.
Did You Overpay or Underpay? A Decision Framework
This is the question that actually matters, and it has a clear answer based on your marginal bracket. Understanding where the 22 percent flat rate sits relative to your real bracket is the core of good tax planning for anyone with variable compensation.
You likely overpaid, and will see it back as refund, if:
- Your total household taxable income sits in the 10 or 12 percent federal bracket
- Your bonus was your only large income event this year
- You have significant itemized deductions or above-the-line deductions not reflected in your W-4
You likely underpaid, and should expect a balance due, if:
- Your marginal federal bracket is 24 percent or higher
- Your combined income with a spouse pushes you into 32 or 35 percent territory
- You received a bonus plus RSU vesting in the same year
- You have 1099 side income with no withholding attached
A taxpayer in the 32 percent bracket who received a $50,000 bonus had $11,000 withheld federally. The actual federal tax on those dollars is $16,000. That is a $5,000 shortfall sitting quietly on the books until April, and it is the single most common reason high earners get surprised by a balance due.
KDA Case Study: Senior Engineer With a Year-End Bonus and RSUs
A client we will call Marcus is a senior software engineer in Santa Clara County earning $218,000 in base salary. In December, he received a $46,000 performance bonus. Earlier that same year, $94,000 of restricted stock units vested. Both events were withheld at the flat 22 percent federal supplemental rate. Marcus assumed he was covered because he never adjusted his W-4 and had always received small refunds.
He was not covered. With $358,000 of total wage income and a spouse earning $96,000, the household sat squarely in the 32 percent federal bracket. The $140,000 of supplemental wages had been withheld at 22 percent, creating a federal shortfall of roughly $14,000 before state exposure was counted. He also owed Additional Medicare Tax of 0.9 percent on income above the threshold.
We restructured three things before the filing deadline. First, we maxed his 401(k) and his spouse’s plan, moving $47,000 of wages into pretax deferral. Second, we funded a family HSA at the full contribution limit. Third, we bunched two years of charitable giving into a donor advised fund in the bonus year, generating a $28,000 itemized deduction instead of two smaller ones that would have been swallowed by the standard deduction.
The net result: his balance due dropped from an estimated $14,200 to $1,900, and he avoided an underpayment penalty entirely. He paid $3,800 for the engagement and kept roughly $12,300 that would otherwise have gone out the door. That is a 3.2x first-year return.
Ready to see how we can help you? Explore more success stories on our case studies page to discover proven strategies that have saved our clients thousands in taxes.
Five Strategies to Reduce Your Actual Tax on a 2026 Bonus
You cannot change the withholding rate your payroll department applies. You can change how much of that bonus is taxable in the first place. Each of these works best when executed before the bonus is paid, which means the planning window is October through December for most employers.
1. Deferral Into Your 401(k)
Many payroll systems allow a separate deferral election on bonus payments. Directing a portion of the bonus into your traditional 401(k) removes those dollars from current taxable income entirely. An employee in the 32 percent federal and 9.3 percent California bracket who defers $15,000 of a bonus avoids roughly $6,200 in combined current-year tax. Check whether your plan uses your standard deferral percentage automatically or requires a separate bonus election, because the default varies widely by employer.
2. Health Savings Account Funding
If you are enrolled in a qualifying high deductible health plan, the HSA is the only account in the code that is deductible going in, tax free while invested, and tax free coming out for medical costs. Funding it from bonus dollars converts taxable compensation into a triple-advantaged asset. Note that California does not conform on HSA treatment, so the state deduction does not follow the federal one.
3. Nonqualified Deferred Compensation
If your employer offers a 409A deferred compensation plan, you may be able to elect, in advance, to push bonus dollars into a future year. This is useful when you expect a lower-income year ahead, such as a planned sabbatical, a retirement date, or a move out of a high-tax state. The election is irrevocable and must be made before the compensation is earned, so this requires planning a full year ahead.
4. Charitable Bunching
Rather than giving $10,000 annually and taking the standard deduction anyway, concentrate several years of intended giving into the bonus year. A donor advised fund lets you take the full deduction immediately while distributing to charities over time. For a detailed look at how this fits alongside entity and income timing decisions, our California tax strategy hub walks through the broader sequencing framework.
5. Harvesting Capital Losses
Up to $3,000 of net capital losses can offset ordinary income each year, including bonus income, with the remainder carried forward indefinitely. If you are holding underwater positions in a taxable brokerage account, realizing those losses in a high-bonus year is a straightforward offset. Watch the 30-day wash sale window on repurchases.
Red Flags and Common Mistakes
Red Flag Alert: Treating the 22 percent withholding as a settled tax is the most expensive assumption in this entire topic. Taxpayers in the 24, 32, 35, and 37 percent brackets are structurally underwithheld on every bonus they receive, and the gap compounds if they receive bonuses annually without ever adjusting Form W-4.
The second mistake is ignoring underpayment penalties. The IRS can assess a penalty when you have not paid in enough during the year, calculated on Form 2210. The safe harbor rules in IRS Publication 505 protect you if you pay in at least 90 percent of the current year tax or 100 percent of last year’s tax, rising to 110 percent if your prior year adjusted gross income exceeded $150,000.
The third mistake is confusing RSU withholding with bonus withholding. Both are supplemental wages, but RSU shares are frequently sold to cover taxes at the same flat 22 percent, leaving large shortfalls that only surface at filing. If you had both events in one year, assume you are short until you prove otherwise.
Pro Tip: Use the IRS Tax Withholding Estimator in November, then submit a revised Form W-4 with an extra amount on Step 4(c) for your final paychecks. Withholding is treated as paid evenly throughout the year, which can erase a penalty that an estimated payment in December cannot.
California-Specific Considerations
California treats bonuses differently than most states and differently than it treats other supplemental wages. The Employment Development Department sets a 10.23 percent withholding rate on bonuses and stock options, compared to 6.6 percent on other supplemental payments such as commissions paid separately. There is no flat bonus tax at the state level either, just a withholding convention.
California has no preferential treatment for capital gains, no conformity on HSA deductions, and a top marginal rate above 13 percent once the mental health services tax applies. For a Los Angeles or San Francisco employee, the combined federal and state marginal rate on an incremental bonus dollar can exceed 45 percent. That reality changes the math on deferral significantly, because every dollar moved into a 401(k) is saving at that combined rate.
If you moved into or out of California during the year, allocation matters. California taxes residents on all income and nonresidents on California-source income. A bonus earned for work performed in California is generally California-source even if paid after you relocate, which catches a lot of people who move to Texas or Nevada in December.
Special Situations and Edge Cases
Bonuses Above $1 Million
Once your cumulative supplemental wages exceed $1 million in a calendar year, the mandatory 37 percent federal rate applies to the excess. Your employer has no discretion here and cannot use the aggregate method on those dollars. The threshold is cumulative across the year, not per payment, so a $600,000 bonus in March followed by a $600,000 bonus in September crosses it.
Signing Bonus Clawbacks
If you leave a job and have to repay a signing bonus, the tax treatment depends on timing. Repaying in the same calendar year is usually handled by a corrected W-2. Repaying in a later year triggers the claim of right rules under Section 1341, which may allow either a deduction or a credit for the tax you paid originally. This is one of the few areas where doing it yourself almost always costs money.
Multi-State Workers
If you performed services across state lines during the bonus period, some states require allocation based on workdays. Your employer may withhold entirely to one state. The reconciliation happens on your returns, and getting it wrong in either direction creates notice risk.
Step-by-Step: Verify Whether Your Bonus Withholding Was Correct
- Pull your bonus stub: Identify the federal income tax line separately from Social Security, Medicare, and state lines. Takes two minutes.
- Divide federal tax withheld by gross bonus: If the result is close to 22 percent, your employer used the percentage method.
- Estimate your full-year taxable income: Add base salary, bonus, spouse income, RSU vesting value, and side income, then subtract your deduction.
- Find your marginal bracket: Compare that bracket to 22 percent. Any gap is your approximate shortfall rate.
- Multiply the gap by your bonus: A 10-point gap on a $40,000 bonus means roughly $4,000 is owed and not yet paid in.
- Adjust Form W-4 Step 4(c): Spread that amount across your remaining paychecks before December 31.
Ready to Reduce Your Tax Bill?
KDA Inc. specializes in strategic tax planning for business owners, S Corps, LLCs, and high-net-worth individuals. Book a personalized consultation and walk away with a clear plan.
Frequently Asked Questions
Is a bonus taxed at a higher rate than salary?
No. Bonus income is ordinary income taxed at the same graduated rates as your salary. Only the withholding mechanics differ. The flat 22 percent supplemental rate is an administrative convention from Publication 15, not a tax bracket.
Can I ask my employer to withhold more on my bonus?
Your employer cannot deviate from the mandated supplemental rates on the bonus payment itself. You can, however, submit a revised Form W-4 requesting additional withholding on your regular paychecks, which accomplishes the same result.
What if my bonus pushed me into a higher tax bracket?
Only the dollars above the bracket threshold are taxed at the higher rate. If the 32 percent bracket starts at $200,000 and you land at $210,000, only $10,000 is taxed at 32 percent. Your first $200,000 is unchanged.
Do I pay Social Security tax on a bonus?
Yes, until you reach the annual wage base limit. Once your total wages for the year exceed the Social Security cap, the 6.2 percent stops. Medicare at 1.45 percent never stops, and an Additional Medicare Tax of 0.9 percent kicks in above $200,000 for single filers and $250,000 for joint filers.
The bonus you negotiated is worth whatever survives the plan you built around it, not whatever survives payroll software.
This information is current as of 10/18/2026. Tax laws change frequently. Verify updates with the IRS or FTB if reading this later.
Book Your Tax Strategy Session
If your compensation includes bonuses, commissions, or equity, the flat withholding rate on your stub is almost certainly wrong for your actual bracket, and the difference is sitting on your return right now. Our team maps your full-year income, finds the deferral and deduction levers that still have time to work, and tells you exactly what to change before December 31. Click here to book your consultation now.



