
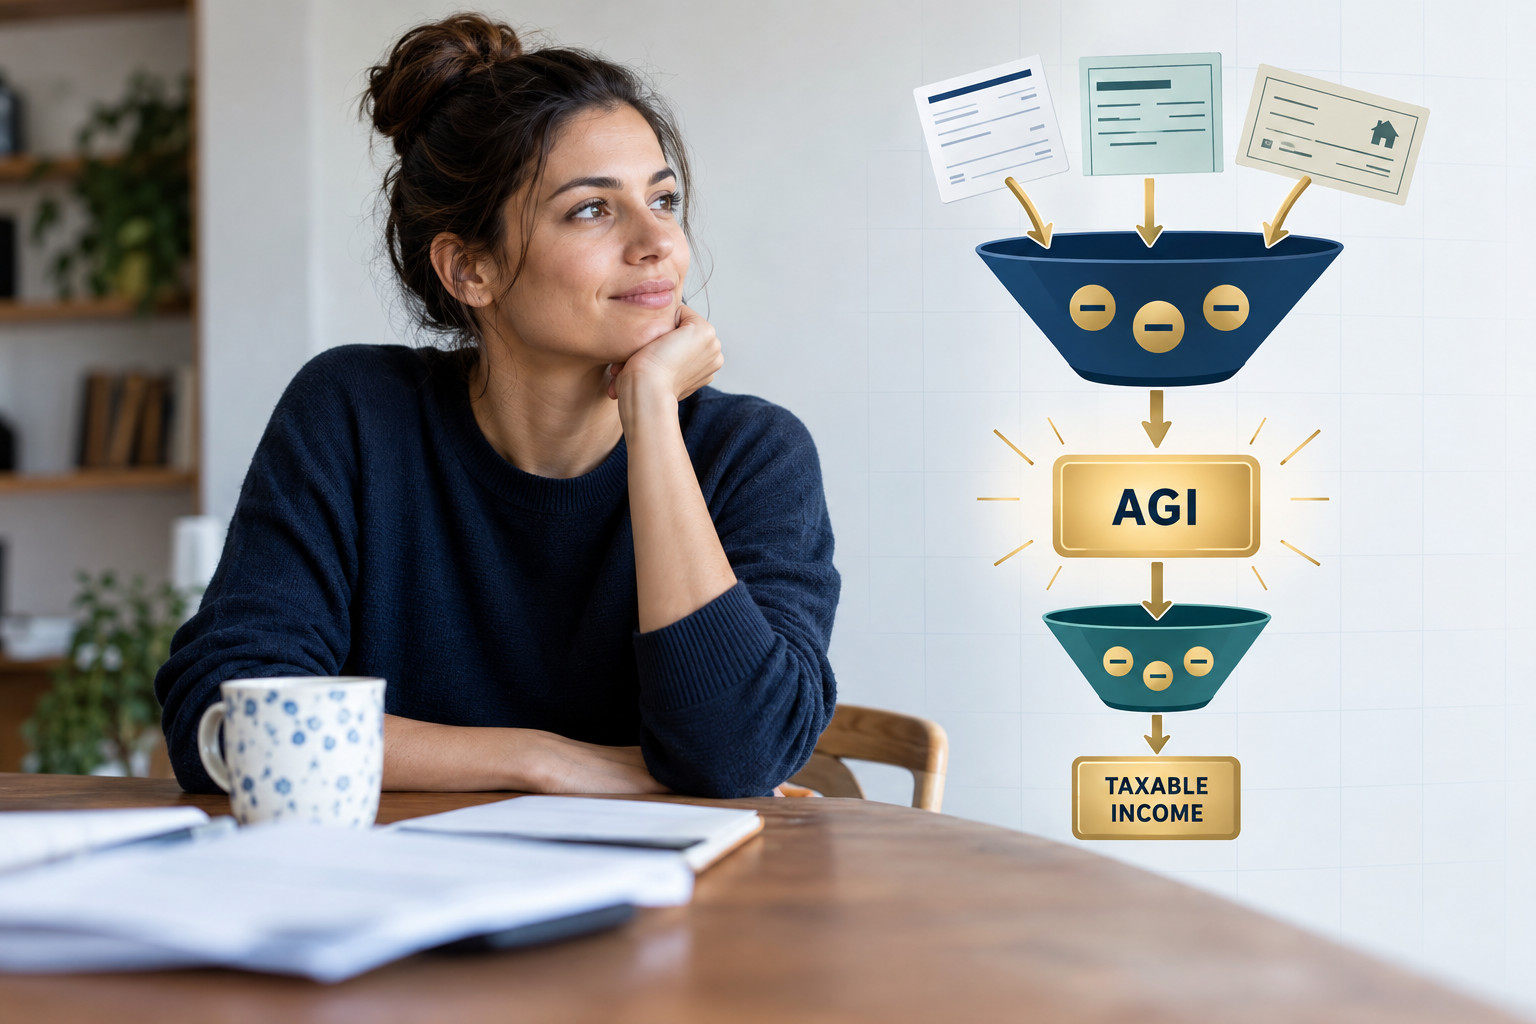
Here is a number that should bother you: the IRS processes more than 160 million individual returns a year, and a large share of the math errors flagged on those returns trace back to one conceptual mix-up. People confuse adjusted gross income with taxable income, plug the wrong figure into the wrong box, and either overpay or trip a notice. So is AGI and taxable income the same thing? No. They are two separate numbers that sit on two different lines of your Form 1040, and the gap between them is where almost every real planning opportunity lives. Treat them as one number and you will miss deductions, blow through credit phaseouts, and misjudge your actual tax bracket by a wide margin.
Quick Answer
Adjusted gross income (AGI) is your total income minus a specific list of adjustments allowed before deductions. Taxable income is your AGI minus your standard or itemized deduction and the qualified business income deduction. AGI is always the larger of the two, and taxable income is the number your tax rate is actually applied to.
Is AGI and Taxable Income the Same? What Each Number Actually Measures
They sit on the same form, two lines apart, and they do completely different jobs. One is a gatekeeper. The other is a price tag.
AGI is the eligibility number
Adjusted gross income is everything you earned during the year, from wages to rental profit to interest to crypto gains, reduced by a short, legally defined set of adjustments. You will find it on line 11 of Form 1040. The IRS uses AGI as the measuring stick for dozens of eligibility tests. Roth IRA contribution limits, the child tax credit, education credits, the premium tax credit on marketplace health insurance, rental loss allowances, and Medicare Part B surcharges all key off AGI or a close cousin called modified AGI.
Taxable income is the billing number
Taxable income appears on line 15. It is what remains after you subtract either the standard deduction or your itemized deductions, plus the Section 199A qualified business income deduction if you qualify. This is the figure that gets run through the tax brackets. Your marginal rate is determined here, not at AGI.
Think of it this way. AGI decides which doors are open to you. Taxable income decides what you pay once you walk through them. A consultant with $148,000 of AGI and $118,000 of taxable income is taxed on the smaller number but screened for credits on the larger one. That distinction costs people thousands every filing season.
Key Takeaway: AGI opens or closes tax benefits. Taxable income sets the bill. Lowering AGI often saves more than lowering taxable income because it unlocks benefits you were otherwise phased out of.
How Gross Income Becomes AGI: The Adjustments Most People Skip
The adjustments that convert gross income into AGI are listed on Schedule 1 of the 1040. They are frequently called above the line deductions because they sit above the AGI line. The critical feature is that you claim them whether you itemize or not. You do not have to give up your standard deduction to use them.
The adjustments that move the needle
- Deductible traditional IRA contributions: up to $7,000 for 2026 filers under 50, $8,000 if you are 50 or older, subject to income limits when you are covered by a workplace plan. See IRS Publication 590-A.
- Health savings account contributions: available if you carry a qualifying high deductible health plan, and deductible even without itemizing.
- Self-employed retirement contributions: SEP IRA and solo 401(k) employer contributions for 1099 earners and single member LLCs.
- One half of self-employment tax: if you paid $18,400 in SE tax, $9,200 comes straight off gross income.
- Self-employed health insurance premiums: often $9,000 to $22,000 for a family paying on the open market.
- Student loan interest: up to $2,500, with a phaseout.
- Educator expenses: $300 per qualifying teacher.
Here is what that stack looks like in practice. A freelance designer grosses $132,000. She contributes $7,000 to a traditional IRA, $4,300 to an HSA, deducts $9,100 as the employer half of her self-employment tax, and writes off $11,600 in health premiums. Her AGI lands at $100,000. She did not itemize a single thing. She simply used adjustments that exist above the line, and in the process she pulled herself under several phaseout thresholds she would otherwise have exceeded.
Myth bust: Many W-2 employees believe above the line adjustments are only for the self-employed. Wrong. IRA contributions, HSA contributions, student loan interest, and educator expenses are all available to wage earners who never file a Schedule C.
KDA Case Study: The 1099 Consultant Who Misread Her Own Return
Priya, 41, runs a solo marketing consultancy in Orange County as a single member LLC. In her prior filing year she grossed $186,000 in client revenue and $42,000 in business expenses, leaving $144,000 of net profit. Her previous preparer ran a clean, correct return and stopped there. No planning. Priya saw taxable income of roughly $121,000 on her 1040 and assumed that was the figure governing everything, including her eligibility to make a Roth IRA contribution and her ability to claim the child tax credit for her two kids. She was wrong on both counts, because both tests run off AGI, which sat near $137,000.
When she came to KDA, we rebuilt the plan around the AGI line instead of the tax bracket. We opened a solo 401(k) and funded $29,500 between employee deferral and employer profit sharing. We added a $4,300 HSA contribution. We corrected the self-employed health insurance deduction her prior preparer had buried on Schedule C instead of Schedule 1, which was costing her the above the line benefit. Combined, those moves dropped AGI from $137,000 to roughly $99,000.
The federal and California tax reduction came to $13,870 for the year. She also regained full child tax credit eligibility and cleared the direct Roth contribution threshold. Her fee for the planning engagement and return preparation was $3,900, which works out to a 3.6x first year return, before counting the compounding value of $29,500 now sitting in a retirement account instead of the US Treasury.
Ready to see how we can help you? Explore more success stories on our case studies page to discover proven strategies that have saved our clients thousands in taxes.
From AGI to Taxable Income: The Second Subtraction
Once AGI is locked, two more things come off before you reach taxable income. This is the step where the standard deduction debate actually happens, and where most people stop optimizing far too early. If you want this layer structured properly year after year rather than reconstructed every April, our tax planning services exist precisely for that reason.
Standard deduction or itemized deductions
You take the larger of the two. Itemized deductions include mortgage interest, state and local taxes subject to the SALT cap, charitable contributions, and medical expenses exceeding 7.5 percent of AGI. Note that last one carefully. The medical threshold is a percentage of AGI, which means lowering AGI makes more of your medical costs deductible. The two numbers are linked.
The qualified business income deduction
Owners of pass-through entities, including sole proprietors, partnerships, S corporations, and most LLCs, may deduct up to 20 percent of qualified business income under Section 199A. It comes off after AGI and before taxable income. It does not reduce AGI, which surprises people constantly. A business owner with $150,000 of AGI and a $30,000 QBI deduction still has $150,000 of AGI for every phaseout test in the code.
Side by side
| Factor | Adjusted Gross Income | Taxable Income |
|---|---|---|
| Form 1040 line | Line 11 | Line 15 |
| Calculated as | Total income minus adjustments | AGI minus deductions and QBI |
| Determines tax brackets | No | Yes |
| Determines credit eligibility | Yes | No |
| Used for IRA and Roth limits | Yes (modified AGI) | No |
| Used by lenders and FAFSA | Yes | Rarely |
| Can be zero or negative | Rarely | Yes |
Why AGI Quietly Controls Credits, Phaseouts, and Medicare Premiums
This is the part generic articles skip. AGI is not just a waypoint on the form. It is the trigger for a long list of cliffs, and crossing one by $500 can cost far more than $500.
Phaseouts that key off AGI or modified AGI
- Roth IRA contributions: phase out and then disappear entirely above the modified AGI range for your filing status.
- Child tax credit: reduced by $50 for every $1,000 of modified AGI above $200,000 single or $400,000 married filing jointly.
- $25,000 rental real estate loss allowance: phases out between $100,000 and $150,000 of modified AGI for active participants, per IRS Publication 925.
- Net investment income tax: the extra 3.8 percent applies above $200,000 single or $250,000 joint modified AGI.
- IRMAA Medicare surcharges: retirees pay higher Part B and Part D premiums based on AGI from two years prior.
Here is a real cliff in action. A landlord with $152,000 of modified AGI and a $21,000 passive rental loss gets to deduct exactly zero of it this year. The same landlord who contributes $7,000 to a traditional IRA and $5,000 to an HSA drops to $140,000 and frees up $5,000 of that loss immediately, with the rest suspended and carried forward. Same property, same tenants, different sequencing.
If you want a quick read on how these layers hit your actual rate, run your numbers through this tax bracket calculator before you make year-end moves rather than after.
Pro Tip: When you are within $10,000 of a phaseout threshold, every dollar of AGI reduction is worth far more than its nominal tax value. Prioritize above the line moves first.
California Does Not Use Your Federal AGI
Here is a section almost no national article covers, and it matters enormously if you file in California. Your California AGI on Form 540 is a separate calculation. The state does not conform to the federal treatment of several items, which means two different AGI figures on two different returns in the same year.
Common federal to California differences
- HSA contributions: deductible federally, not deductible for California purposes. Your state AGI will be higher.
- Depreciation: California does not conform to federal bonus depreciation, and its Section 179 limit is dramatically lower.
- Health savings account earnings: taxable to California, reportable each year.
- Certain retirement and fringe benefit items: handled through Schedule CA adjustments.
The practical consequence is that a California filer can be under a federal phaseout and over a state one at the same time. For business owners juggling multiple entities, this is also where federal and state strategies diverge, and the California business owner tax strategy hub walks through how those layers stack. Verify your Schedule CA adjustments with the California Franchise Tax Board before you assume conformity.
Red Flag Alert: The Mistakes That Cost Real Money
Red Flag Alert: Using taxable income where the form asks for AGI. This shows up most often on financial aid applications, marketplace health insurance applications, and e-file identity verification. The IRS asks for prior year AGI to verify your identity when you e-file. Enter taxable income instead and your return gets rejected, sometimes repeatedly, sometimes days before the deadline.
Four more mistakes we see every season
- Assuming the QBI deduction lowers AGI. It does not. It sits below the AGI line and has no effect on credit eligibility.
- Burying self-employed health insurance on Schedule C. It belongs on Schedule 1 as an above the line adjustment. Placed wrong, it distorts your net profit, your self-employment tax base, and your AGI.
- Chasing itemized deductions while ignoring adjustments. A $7,000 IRA contribution beats $7,000 of extra itemizing when you are near a phaseout, because only one of them lowers AGI.
- Forgetting that modified AGI is a third number. MAGI adds certain items back to AGI, and the definition changes depending on which benefit you are testing. There is no single MAGI.
For the full definitional walkthrough of income types and adjustments, IRS Publication 17 remains the clearest free reference available.
Step by Step: Calculate Both Numbers in 15 Minutes
- Total your gross income: W-2 wages, 1099-NEC and 1099-K revenue, interest, dividends, capital gains, rental profit, retirement distributions, and K-1 income. Takes about 5 minutes with your documents in hand.
- List your Schedule 1 adjustments: IRA, HSA, SEP or solo 401(k), half of self-employment tax, self-employed health insurance, student loan interest.
- Subtract adjustments from gross income: the result is your AGI. Write it down. This is your eligibility number.
- Compare standard versus itemized: total your mortgage interest, capped state and local taxes, charitable gifts, and medical costs above 7.5 percent of AGI. Take whichever is larger.
- Subtract your deduction and any QBI deduction: the result is taxable income. Apply the brackets to this figure only.
Should you focus on AGI or taxable income this year?
Prioritize lowering AGI if:
- You are within $15,000 of a credit or contribution phaseout
- You have passive rental losses being limited
- You buy health coverage through the marketplace
- You are within two years of Medicare enrollment
Focus on taxable income if:
- Your AGI is far above every phaseout and nothing can realistically pull it under
- You are weighing bunching charitable contributions into one year
- You are managing a QBI deduction near the specified service business threshold
Ready to Reduce Your Tax Bill?
KDA Inc. specializes in strategic tax planning for business owners, S Corps, LLCs, and high-net-worth individuals. Book a personalized consultation and walk away with a clear plan.
Frequently Asked Questions
Can taxable income be lower than AGI by more than the standard deduction?
Yes. The QBI deduction comes off after the standard or itemized deduction, so a pass-through owner can see a gap far wider than the standard deduction alone. A sole proprietor with $160,000 AGI, a $30,000 standard deduction, and a $26,000 QBI deduction reports $104,000 of taxable income.
Can taxable income be zero while AGI is substantial?
Absolutely. A retired couple with $31,000 of AGI and a standard deduction larger than that figure reports zero taxable income and owes no federal income tax. AGI stays positive, taxable income floors at zero, and it never goes negative on the 1040.
Which number do lenders and schools ask for?
AGI, nearly always. Mortgage underwriters, the FAFSA, marketplace subsidy calculations, and most income-driven student loan repayment plans all run off AGI or a modified version of it. Taxable income rarely appears outside the tax return itself.
Does reducing taxable income help me qualify for more credits?
No, and this is the single most expensive misunderstanding in this entire topic. Credit eligibility is tested at AGI or modified AGI. You can cut taxable income to the floor and still be fully phased out of a credit because your AGI never moved.
Here is the line worth remembering: your tax bracket is set by taxable income, but your tax life is governed by AGI.
Stop Guessing Which Number Is Costing You
If you have never had anyone map your return line by line and show you exactly where your AGI sits relative to every phaseout you are eligible for, you are almost certainly leaving money on the table. Our team builds the plan before the year closes, not after, when the only thing left to do is report what already happened. Book your tax strategy session now and get a clear picture of both numbers, what moves them, and what each move is worth to you in real dollars.
This information is current as of 10/23/2026. Tax laws change frequently. Verify updates with the IRS or FTB if reading this later.



